AI Computing Power Drives Continuous Evolution of Optical Communication
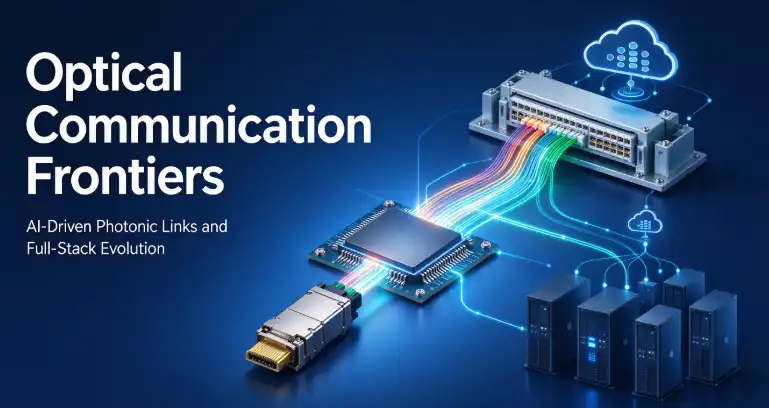
AI large model training, intelligent computing center cluster interconnection, and cloud business expansion are reshaping the development logic of the optical communication industry. In the past, growth in optical communication mainly came from wide-area communication construction such as 5G and fiber-to-the-home; today, the core driver of industry prosperity is the massive, low-latency data exchange within AI computing clusters. From high-speed optical modules and integrated optical chips to next-generation specialty fibers, the entire industry chain is rapidly iterating technologically, and optical-electrical interconnection has become an indispensable underlying artery of computing infrastructure.
I. High-Speed Optical Modules: 800G in Large-Scale Deployment, 1.6T Enters Commercial Introduction Phase
Optical modules are responsible for the mutual conversion of electrical and optical signals, serving as core components for data transmission between GPUs and switches. In 2026, 800G optical modules remain the market's primary delivery product, deployed in large AI data centers both domestically and internationally; 1.6T optical modules have completed verification with leading customers and entered small-batch supply stage, but large-scale volume production is still constrained by downstream switch and server hardware compatibility. The industry generally expects large-scale ramp-up to gradually release over the next 1-2 years.
Alongside rate upgrades, the industry is exploring next-generation interconnection architectures: LPO linear direct drive, NPO near-package optics, and CPO co-packaged optics.
- NPO (Near-Package Optics): The optical engine is placed next to the switching chip, shortening high-speed electrical links, balancing low power consumption and high density, while retaining the ability to replace and maintain modules. The industry considers this the next-generation solution with the highest certainty of implementation;
- CPO (Co-Packaged Optics): Integrates the optical engine and switching chip on the same substrate, offering theoretically optimal power consumption, but faces engineering challenges in heat dissipation, field maintenance, and supply chain compatibility. The large-scale commercial cycle is longer, currently focused on sample R&D and verification.
Regarding modulation formats, high-speed modules currently mainstream adopt PAM4. For higher bandwidth scenarios, higher-order modulation technologies such as PAM6 and PAM8 are being evaluated in laboratory and sample stages.
II. Optical Chips and Optoelectronic Integration: Silicon Photonics and Thin-Film Lithium Niobate Drive Localization
Optical chips are the core of optical modules and were previously a relatively weak link in the domestic industry chain. Now, three major material routes are developing in parallel:
- Silicon Photonics (SiPh): Leverages mature CMOS semiconductor processes, suitable for large-scale mass production and cost reduction, making it the mainstream solution for 800G and 1.6T high-speed modules. Silicon itself cannot emit light and requires indium phosphide lasers as a light source. It is primarily responsible for signal modulation and optical path processing, with penetration rates continuously rising in AI data center short-reach interconnection scenarios.
- Indium Phosphide (InP): Traditional active optical chip solution that can directly fabricate lasers and detectors, with clear advantages in long-haul coherent transmission scenarios, widely used in backbone networks and metropolitan area network high-speed transmission.
- Thin-Film Lithium Niobate (LNOI): Next-generation modulation chip material featuring high bandwidth, low loss, and low power consumption, suitable for future 3.2T and above ultra-high-speed modules, currently in industrialization verification stage.
Domestic manufacturers such as Accelink, Shijia Photons, and HGTECH are continuously advancing independent R&D of high-speed optical chips, steadily improving self-sufficiency rates for high-end devices and reducing dependence on overseas supply chains.
III. Fiber Optic Technology Innovation: Hollow-Core Fiber and Multi-Core Fiber for Next-Generation Computing Networks
Conventional silica solid-core fibers have supported global communication networks for decades. Facing the ultra-high-speed, low-latency demands of AI computing centers, new specialty fibers have become a frontier R&D hotspot.
Hollow-Core Fiber: Signals transmit through air holes in the fiber rather than glass medium, significantly reducing nonlinear effects and transmission latency. In 2026, domestic companies achieved multiple milestone results: Yangtze Optical Fibre and Cable achieved ultra-low loss of 0.032dB/km with anti-resonant hollow-core fiber, and FiberHome completed continuous drawing of 110-kilometer single-drum hollow-core fiber. Hollow-core fiber has already been deployed in intelligent computing interconnection and metropolitan area network pilot projects. It is expected to be used for long-reach interconnection scenarios within ultra-large-scale computing clusters in the future, but due to high costs, it will not comprehensively replace ordinary single-mode fiber in the short term.
Additionally, multi-core fiber and few-mode fiber utilize space division multiplexing technology to achieve multi-channel parallel signal transmission within a single fiber, addressing the pain point of massive fiber routing congestion in data centers. Leading module manufacturers and fiber companies are jointly developing relevant industry standards for high-density computing cluster routing scenarios.
IV. Other Frontier Directions: All-Optical Switching, Coherent Communication, and 6G Pre-Research
- All-Optical Circuit Switches (OCS): Data centers adopt optical layer direct switching internally, eliminating multiple optical-electrical conversions, reducing latency and power consumption. Currently mainly used for trial deployment in large intelligent computing centers.
- Long-Haul Coherent Transmission: Backbone networks and cross-regional data center interconnection continue to upgrade 400G/800G coherent optical modules, enhancing single-fiber transmission capacity.
- 6G Supporting Optoelectronic Devices: Terahertz communication, inter-satellite laser communication, and other technologies continue experimental verification. These belong to mid-to-long-term frontier layouts, with a considerable period remaining before commercialization.
V. Industry Reality Challenges
Alongside rapid technological iteration, the industry chain still faces numerous engineering challenges:
- High-speed optical chip capacity is tight, with upstream core material supply constraints limiting high-end module capacity release;
- Higher bandwidth solutions require exponentially increasing demands on PCB, packaging, heat dissipation, and test equipment;
- New technologies like CPO and hollow-core fiber need to balance performance, reliability, and cost, with commercial deployment cycles far longer than sample R&D cycles.
Conclusion
The optical communication industry is currently at a critical stage transitioning from "communication infrastructure supporting components" to "core components of computing infrastructure." In the short term, 800G continued volume ramp-up and gradual 1.6T introduction form the main thread; in the mid-to-long term, silicon photonics integration, NPO, hollow-core fiber, and other technologies will continuously support growing AI computing network bandwidth demands. The domestic optical communication industry chain has already achieved global competitiveness in high-speed modules and specialty fibers, continuously participating in global data center project construction.